|

News
SDBA Updates
SDBA Events
Online Education
Banking Trades Statement on Clarity Act Cloture Vote
September 15, 2026
WASHINGTON — Following today’s Senate cloture vote on the Digital Asset Market Clarity Act, the American Bankers Association, Association of Military Banks of America, Bank Policy Institute, Consumer Bankers Association, Financial Services Forum, Independent Community Bankers of America, Mid-Size Bank Coalition of America and National Bankers Association issued the following joint statement.
"The nation’s banks continue to support creating a strong, durable regulatory framework for digital assets that will set the course for U.S. global leadership for decades to come. We believe Congress can accomplish that goal while protecting the bank lending that drives economic growth. As lawmakers consider next steps, we encourage them to adopt targeted changes to stablecoin yield policy. We stand ready to work with all stakeholders to achieve this important goal.”
ABA President & CEO Rob Nichols
September 16, 2026
 To ABA member bank CEOs:
The U.S. Senate today failed to obtain the 60 votes necessary to advance the Clarity Act. Because of limited legislative time before the midterm elections, the path for a comprehensive regulatory framework for digital assets this Congress remains unclear.
Without legislation to follow, federal regulatators will likely step forward and try and fill the gap, and the Genius Act will remain the law of the land when it comes to stablecoins.
As you know, we strongly support the goal of bringing digital assets into the regulatory perimeter, and we are committed to working with members of Congress to craft a framework that embraces innovation without undermining the economy.
Today’s vote is a signal that senators still have real questions about many provisions of the Clarity Act, including the concern we raised months ago about crypto companies circumventing congressional intent and offering interest-like rewards for holding stablecoins.
ABA and our partners in the state association alliance and other trade groups have worked tirelessly to educate lawmakers on the potentially devastating consequences for local lending if that loophole isn’t closed. In personal meetings, phone calls and letters to the Hill, bankers across the country urged senators to strengthen that section of the Clarity Act or risk a reduction in small business, home and ag loans. That advocacy—through your local voices as trusted community members—made a real difference in this debate.
As lawmakers decide the next steps for this legislation, we will need your continued engagement as we push for sensible rules around digital assets that are clear and fair.
Thanks again for your efforts, and we will keep you updated on our progress.
ABA Banking Journal: House committee advances ABA-backed bills on state lending rate caps, CFPB reform
September 16, 2026
 The House Financial Services Committee today voted 31-18 to advance legislation to prevent states from imposing interest rate caps on loans from out-of-state state-chartered banks and credit unions. Ahead of the vote, the American Bankers Association joined nearly a dozen financial sector associations in voicing support for the bill.
The committee also voted 28-21 to advance legislation to change how the Consumer Financial Protection Bureau is funded and redefine its ability to regulate unfair, deceptive, or abusive acts or practices, or UDAAP.
State lending rate caps
Under current law, states can opt out of the federal Depository Institutions Deregulation and Monetary Control Act, or DIDMCA, allowing them to establish restrictions on loans made by state-chartered banks. The American Lending Fairness Act (H.R. 7866) by Rep. Warren Davidson (R-Ohio) would prevent states from using the opt-out to impose interest rate caps on loans from out-of-state state-chartered financial institutions. A companion bill was introduced in the Senate by Sen. Bernie Moreno (R-Ohio).
In a letter to committee leaders, the associations said the decision by Colorado and Oregon to use the DIDMCA opt-out to impose their jurisdiction on loans to their residents by state institutions chartered in other states “directly contravenes Congress’ original, limited intent” in DIDMCA.
“Passage of federal legislation in the form of the American Lending Fairness Act would not only ensure keeping existing parity between lending institutions on the national and state level and clarity as to the limited scope of DIDMCA’s opt-out provision, it would also provide certainty that the dual banking system is preserved,” the associations said.
CFPB reform
The Consumer Financial Protection Accountability and Reform Act of 2026 (H.R. 10184) would change how the CFPB is funded and operated.
The bureau is unique among federal agencies in that the bureau director requests funding from the Federal Reserve. The bill would instead subject the bureau to congressional appropriations, which Republicans say would make it more accountable to elected officials.
The legislation would also change how the bureau regulates UDAAP. For example, the CFPB would be required to more clearly define the “abusive” standard and no longer be permitted to interpret UDAAP to include discriminatory practices.
ABA supported the legislation along with two other bills advanced by the committee:
- The Civil Investigative Demand Reform Act (H.R. 1653), which would reform the process the CFPB uses to issue civil investigative demands to financial services providers. The vote was 29-20.
- The Taskforce for Recognizing and Averting Payment Scams, or TRAPS, Act (H.R. 4936) would direct the Secretary of the Treasury to establish, within 90 days of enactment, a Task Force for Recognizing and Averting Payment Scams. The vote was unanimous.
Original Article
ABA Banking Journal: Senate Ag Committee advances Farm Bill
September 16, 2026
 The Senate Banking Committee today voted 12-11 to advance the Farm Bill, with the current version of the legislation including several provisions supported by the American Bankers Association.
The Farm Bill previously stalled in committee with Sen. Mitch McConnell’s (R-Ky.) absence leaving Republicans without the majority needed to advance the legislation. Committee Democrats oppose the bill in its current form because it does not include a two-year delay of changes to the Supplemental Nutrition Assistance Program, or SNAP. McConnell returned this week and voted with his GOP colleagues to report the bill out of committee.
Among the ABA-backed provisions, the Senate version of the Farm Bill would increase Farm Service Agency, or FSA, Guaranteed Farm Ownership Loan Program limits to $3.5 million and FSA Guaranteed Farm Operating Loan Program to $3 million. It would also increase the FSA Direct Farm Ownership Program loan limit amounts to $850,000 and FSA Direct Farm Operating Loan Programs to $750,000.
Other provisions supported by ABA would create a guaranteed loan program for precision agriculture purchases, expand eligibility for the definition of a “qualified beginning farmer or rancher” by removing the “blood relation” requirement, and raise caps in state agricultural mediation from $500,000 to $700,000 per year and an appropriations limit of $10 million. It would also establish the USDA Express Loan Program to help family farmers and ranchers access credit efficiently.
Along with the changes, senators removed multiple Farm Credit System provisions from the House versions of the Farm Bill that ABA did not support, including making the Farm Credit Administration the sole regulator of the Farm Credit System and having Farm Credit Institutions on 24-month examination cycles rather than 18-month examination cycles.
“We thank the Senate Agriculture Committee for advancing the 2026 Farm Bill,” ABA President and CEO Rob Nichols said. “This important legislation contains provisions that strengthen rural access to credit, including long-overdue increases to Farm Service Agency guaranteed loan limits. We urge the full Senate to act quickly so farmers, ranchers and rural communities can benefit from the certainty and support this bill provides.”
Original Article
SDBA Chair Nate Franzén Receives Bruning Award
 The South Dakota Bankers Association is proud to congratulate our Chair, Nate Franzén, on being named the 2026 Bruning Award recipient by the American Bankers Association!
The Bruning Award is one of the banking industry’s highest honors recognizing agricultural bankers for exceptional leadership and a commitment to providing credit and financial guidance to America’s farmers and ranchers. And we can’t think of anyone more deserving.
With more than 32 years in agricultural banking, Nate has been an advocate for agriculture, rural communities and the future of banking. His leadership extends from South Dakota to the national and international levels, and we are fortunate to have him serving as a leader for our association and our industry.
Nate, congratulations on this well-deserved recognition! We’re proud to call you our Chair and even prouder to celebrate this incredible achievement with you.
About the Bruning Award
Since 1997, the Bruning Award, named after its first recipient, Nebraska banker Frank Bruning, recognizes bankers that demonstrate outstanding leadership and dedicated service to providing credit and guidance to farmers, ranchers and their fellow agricultural bankers.
ABA Banking Journal: Banks’ wealth units pursue AI — carefully
'Some of the best ideas have come from junior employees doing the analytical work who often understand the technology better.'
September 14, 2026 | John Hintze
 Citi Wealth describes its AI-generated avatar Citi Sky as an “always-on AI-powered member of the Citi Wealth team.” In a video demonstration, the avatar discusses with a human client the options to renew a maturing CD and submits the client’s choice to be executed. It then confirms the college fund for the client’s daughter is on track, noting that she must be excited about her college acceptance.
The client asks about other considerations, the avatar notes a recent rate cut that could provide mortgage refinancing opportunities and offers to schedule an appointment with the customer’s advisor.
Citi Sky applies generative AI, which creates new and original content, and in this case enables the avatar to interact directly with wealth-department customers.
“Over time, the new capability will create a more intuitive, responsive and personalized wealth experience — elevating the Citi Wealth client journey while empowering advisors,” Citi says, noting the rollout in phases to Citigold clients.
As one of the largest national banks, Citi’s customer-facing generative AI agent is leading the banking pack, according to the results of an ABA survey published in March. Surveying 250 banks with assets between $75 million and $600 billion, ABA found that early use cases are narrow, internal and efficiency-focused, prioritizing low risk applications that support human judgment. It also found that most banks remain focused on traditional AI — mainly machine learning.
“Generative AI, by contrast, remains earlier stage and tightly controlled, with significantly lower confidence in near term benefits due to data security, accuracy and regulatory concerns,” according to the report.
Nevertheless, the results of the survey point to the conclusion that “the advantage will accrue to banks that build internal understanding and governance capabilities through controlled use.”
United Community Bank has taken an active if cautious approach to implementing AI. The community bank operating across six Southern states is focused now on using the technology to augment its current capabilities, says Abraham Cox, chief consumer and small business banking officer at the $28 billion-asset bank.
Bankers in its wealth management business, like the rest of the bank, are now using Microsoft Copilot internally to develop presentations, take notes, and otherwise make their communications more efficient, whether internally or with clients, as well as improve the speed and quality of generating insights into customers.
“That allows our private bankers, our advisors, to be able to spend more time with customers on more value-added types of duties and responsibilities,” Cox said.
Cox says the bank does not anticipate deploying AI involved in wealth-customer interactions or decision-making anytime soon. Its CIO, however, is leading efforts to identify potential internal projects and third-party tools that would apply AI to reduce fraud risk, administrative work and improve the customer experience. Facilitating employees’ access to and understanding of human-resource policies is one consideration. On the wealth front, for example, Cox adds, AI could enable bankers to more efficiently review and apply the bank’s mortgage guidelines and policies.
“In a controlled, internal fashion, can we use AI to digest all this information?” Cox asks. “Then once tested, AI would enable bankers to understand quickly what the policy is for loans offered to wealth customers.”
South State Bank has given all employees within the bank access to Copilot and some to Copilot Premium. The latter unlocks AI functionality inside Microsoft Office, such as specialized AI assistants that, for example, gather, summarize and analyze complex data.
As the technology becomes more widespread and newsworthy, examiners are digging deeper into things such as contracts, validation techniques and more.
“We’re working on giving everybody a baseline understanding of the tools” within a certain timeline, said George King, EVP of the $68 billion Florida-based company.
The institution recently started taking a more granular approach to determine how copilot can be applied to specific job functions, by pairing bankers in those roles with IT professionals to customize existing AI tools.
“So, if you’re a relationship manager, what can we do with the existing tools to create efficiency specific to your job function and improve our client experience?” he asks.
South State is evaluating third-party options that employ AI, such as a tool it recently acquired independently from its existing wealth-services vendors that evaluates and summarizes trust and estate documents and provides a user-friendly presentation for clients. Such presentations could have previously taken financial planners 10 or more hours to create.
“We would not have had the capacity to devote that level of resources to a client,” he said.
Cox said that his bank’s core wealth vendors have yet to deploy AI capabilities in their platforms. And while the bank has yet to adopt wealth-specific AI tools, he said, it is looking at third-party offerings, such as Jump’s AI assistant that facilitates note-taking and preparing for meetings.
More choices may soon arrive. Anthropic, for example, announced in May that it was issuing 10 “ready-to-run” agent templates covering what it calls the most time-consuming work in financial services, including building pitchbooks, screening KYC and closing books at month’s end.
The largest banks are already leaps ahead in terms of AI assistants. BNY’s Eliza platform, launched in 2023, has deployed 140 autonomous AI agents, which it refers to as digital employees, to aid its bankers across a variety of tasks. It is currently building agents to analyze complex trust documents, and while such applications are not new, says Alvina Lo, head of advice, planning and fiduciary services at BNY Wealth, the agents feed the information back into BNY’s proprietary wealth management system.
“That will help tremendously with work flow,” Lo says, adding that the bank is also considering AI agents to streamline trust administration reviews, account onboarding, distributions and wealth-account terminations.
BNY is considering agentic AI to help trust officers to determine whether the distributions are in line with trust agreements and with balance-sheet needs of beneficiaries, and to recommend issues to consider for specific clients. Lo adds the bank may opt for third-party tools in well-tread areas such as estate planning. For more specific functions, particularly in complex areas such as trust, BNY employees often point the way.
“Some of the best ideas have come from junior employees doing the analytical work who often understand the technology better,” Lo says.
Given AI’s tendency to “hallucinate,” Lo emphasizes that a trust officer must review all decisions generated by AI agents before they are acted upon.
Banks must also consider compliance risk. Ryan Miller, senior counsel of innovation policy at ABA, says regulators typically examine AI through several risk lenses, including model risk, third-party risk, data privacy and security, and the impact of AI models on protected characteristics such as race and gender.
Miller says banks are “well served” by documenting their governance programs, including policies and procedures, formal agendas, minutes for key enterprise meetings and employee training materials/logs. They should also keep records of validation techniques and decisions, and their respective audit trails showing the work.
“Regulators want to see that banks are thinking about the risks presented by traditional AI use and are taking steps to institute appropriate controls,” Miller says. “As the technology becomes more widespread and newsworthy, examiners are digging deeper into things such as contracts, validation techniques and more.”
He adds regulators are anticipated to provide guidance specific to newer forms of AI such as generative and agentic in the near future, and a lot of the same principles will apply.
In terms of next steps, King says, South State Bank is exploring how to pull information across its distinct technology platforms to one place, to further improve efficiency and the client experience. He added that he would like advisors to be able to prepare for client meetings by using AI to summarize information about the family from the bank’s CRM system, topics of recent email correspondence and any public records, as well as suggest topics to address.
“Banks have a tremendous amount of data, but we haven’t been great utilizing it,” King says. “AI should give us a lot more insight into our client base, but that’s going to require accessing a broader range of information.”
Cox sees AI ultimately providing wealth advisors with a better understanding of customer data and customer events.
“It could help us understand money in motion, things that are changing and provide prompt notification for bankers and wealth advisors to better help their clients,” he says.
Contributing editor John Hintze is a financial journalist who writes frequently for the ABA Banking Journal.
Original Article
Abrigo: Why law enforcement relationships matter in fraud investigations
August 26, 2026 | Terri Luttrell, CAMS-Audit, CFCS
What are fraud investigations?
Fraud investigations are the process financial institutions use to identify, analyze, document, and respond to suspected fraudulent activity. They are about much more than investigating a disputed transaction or gathering information to file a claim with a credit card carrier. Today, fraud investigations are an important part of a bank or credit union’s broader financial crime prevention program.
Fraud and AML
That distinction matters because fraud and money laundering increasingly overlap. Fraud proceeds may move through money-mule accounts, shell companies, wire transfers, checks, instant payments, or other channels before being withdrawn or transferred elsewhere. Activity that begins as a fraud investigation may uncover suspicious transactions that require further AML/CFT review and potentially a Suspicious Activity Report (SAR). Likewise, transaction monitoring may identify activity that ultimately points to an underlying fraud scheme.
Historically, many financial institutions managed fraud and AML as separate functions with different responsibilities. That model is changing as the lines between fraud and money laundering become increasingly connected. Fraud teams may identify the predicate criminal activity, while AML teams follow the movement of illicit proceeds and fulfill applicable BSA reporting responsibilities. Sharing information across those functions can give investigators a more complete view of the customer, transactions, and potential financial crime.
This crossover also reinforces why relationships with law enforcement matter. A financial institution may initially see a customer loss or suspicious account, while law enforcement may be investigating the same activity as part of a larger fraud network. Treating fraud investigations as part of the broader financial crime program helps institutions connect the pieces, appropriately escalate suspicious activity, and provide useful information when law enforcement becomes involved.
CISA News: China-Based Artificial Intelligence Companies Conducting Industrial-Scale Distillation Campaigns Against U.S. AI Companies
September 8, 2026
Executive summary
China-based artificial intelligence (AI) companies are conducting systematic extraction of proprietary functionalities and capabilities of U.S. AI companies’ models through industrial-scale knowledge distillation campaigns that form the core—not merely a supplement—of their AI development strategy. While “distillation” is recognized as a legitimate and useful technique in AI research, China-based AI companies are engaging in aggressive, malicious, and targeted distillation activities at an industrial scale that extract restricted proprietary functionalities and capabilities of U.S. frontier AI models. The National Security Agency (NSA), Cybersecurity and Infrastructure Security Agency (CISA), and Federal Bureau of Investigation (FBI) (hereafter referred to as the authoring agencies) are releasing this joint Cybersecurity Advisory to alert organizations about these malicious activities and techniques and recommend mitigations to reduce their potential impact.
Likely with Chinese government awareness, DeepSeek, Moonshot AI, Alibaba, MiniMax, StepFun, and Z.AI extracted billions of tokens across millions of exchanges/requests from U.S. frontier AI models, including variants of Claude, GPT, Gemini, and Grok, since at least late 2024. DeepSeek has conducted organized campaigns since at least 2024 targeting reasoning capabilities, specialized optimizations, and domain-specific functions to train its R1 and V3 models. Alibaba leveraged industrial-scale distillation to improve the company’s Qwen family of AI models. Moonshot AI, MiniMax, Stepfun, and Z.AI also engaged in malicious knowledge distillation of U.S. AI companies’ models.
China-based AI companies route distillation requests through multiple pathways to gain unauthorized access, consequently violating U.S. AI companies’ terms of use. These pathways include native application programming interfaces (APIs), remote cloud providers, and third-party aggregators that automatically obfuscate user metadata to avoid detection. Further, China-based AI companies use a gray market of proxies known as “transfer stations” to bypass U.S. AI companies’ geographic restrictions, breach terms of use, evade safeguards, and undermine traceability. China-based AI companies achieve cost savings for their industrial-scale distillation campaigns through bulk procurement of the U.S. AI companies’ premium subscriptions shared across teams of developers. Advanced industrial-scale distillation tactics include chain-of-thought (CoT) reasoning extraction, automated failover between pathways during blocking attempts, and sophisticated quality evaluation frameworks to detect defensive countermeasures. China-based AI companies that conduct industrial-scale distillation against U.S. AI models see significantly shorter AI development timelines and reduced financial expenditures in training a frontier model.
China-based AI companies deliberately distribute operations across multiple providers, platforms, and pathways to avoid single-point detection. They also attempt to distill the best capabilities and proprietary features of each U.S. frontier model to train their China-based AI models. This represents systematic extraction of proprietary functionalities and capabilities threatening U.S. technological leadership. Addressing industrial-scale distillation merits a coordinated response across the AI ecosystem, including effective information-sharing, spanning the U.S. Government, private industry, and allied nations.
The authoring agencies recommend U.S. AI companies take three immediate actions:
- Implement comprehensive detection and mitigation: Detect anomalous and malicious prompts, accounts, networks, and behaviors. Additionally, monitor subscription-to-usage ratios, immediate maximum usage from new accounts, and enterprise-scale throughput patterns.
- Deploy targeted response changes: Subtly alter responses for suspected malicious distillation attempts to attenuate the payoffs to companies conducting industrial-scale distillation campaigns.
- Establish cross-organization intelligence sharing: Correlate activity across model providers, cloud platforms, and API aggregators to reveal distributed campaigns.
Attribution
Since at least late 2024, China-based AI companies, including DeepSeek (DeepSeek Artificial Intelligence Technology Research Co., Ltd.), Moonshot AI (Beijing Moonshot Technology Co., Ltd.), Alibaba Group, MiniMax (Shanghai MiniMax Co., Ltd.), StepFun (Shanghai Jieyue Xingchen Intelligence Technology Co., Ltd.), and Z.AI, have conducted high-volume knowledge distillation campaigns against several U.S. AI companies. The sheer scale of these campaigns and their sophistication indicate that distillation is not a supplement to these companies’ AI model development, but the critical core of it.
Likely with the knowledge of the Chinese government, the China-based AI sector has turned to a comprehensive distillation strategy in an attempt to bridge the technological and performance gaps between their AI models and U.S. frontier AI models. To access U.S. AI companies’ application programming interfaces (APIs), China-based AI companies use a gray market of API proxies known as “transfer stations” to bypass U.S. AI companies’ regional restrictions, breach terms of use, evade safeguards, and undermine traceability.
DeepSeek
DeepSeek has been conducting an organized distillation campaign against U.S. AI companies’ frontier AI models since at least late 2024 to generate synthetic training data for its models, including R1, released in early 2025. The company targeted specific knowledge domains to extract proprietary functionality and reasoning capabilities to reduce their compute and research costs. DeepSeek’s publicly quoted training costs of $5.6M are misleading as it does not include the true cost of the data acquired through extensive malicious distillation.1
Between late 2024 and mid-2025, DeepSeek distilled specialized training data and capabilities from the following U.S. frontier AI company models to train their R1 and V3 models:
- Claude 3.7
- Claude Sonnet 4
- Claude Sonnet 4.5
- Claude Opus 4.1
- Gemini 2.5 Pro Preview
- Gemini 2.5 Flash Preview
- GPT-4
- GPT-4o
- GPT-4 Mini
- GPT-4 Nano
- GPT-5
- Grok 4
The specific knowledge and capabilities distilled included:
- Legal specialization optimization
- API rule-driven tasks
- Writing using CoT drafts
- Agentic functions
- Question and answer optimization
- Coach/assistant capabilities
- Functional creation optimization
- Supervised fine-tuning (SFT) optimization
- Creative and occupational writing optimization
Moonshot AI
Moonshot AI has conducted a widespread distillation campaign against U.S. frontier AI companies since at least mid-2025. Notably, Moonshot AI extracted significant Claude Fable 5 data to train its Kimi-K3 model and GPT-4o data to train its Kimi-K2 model. The company has used the following models to distill SFT optimization, reinforcement learning (RL), software engineering, and math capabilities:
- Claude Opus 4.1
- Claude Sonnet 3.7
- Claude Sonnet 4
- Claude Sonnet 4.5
- Claude Sonnet 4.5 Thinking
- Claude Fable 5
- GPT-oss-20b
- GPT-3
- GPT-4o
- GPT-4o mini
- GPT-5
- GPT-5 Codex
- GPT-5 Pro
- Gemini 2.5 Flash
- Gemini 2.5 Flash-Image
- Gemini 2.5 Pro
- Nano Banana
- Grok Code Fast-1
Other companies
Several other China-based AI companies, including Alibaba, MiniMax, StepFun, and Z.AI have also leveraged distillation techniques to build their AI models. In late 2025, Alibaba distilled Claude-4, Claude Opus, Claude Sonnet, and GPT-5 to improve their AI models’ software engineering skills, customer service dialogue functionality, image/character creation, and integration of RL, SFT, and distillation capabilities.
In late 2025, MiniMax distilled CoT reasoning, RL, SFT, and software engineering capabilities to improve its M2 model from Claude Code, Claude Sonnet 4, Claude Opus, Gemini 1, Gemini 2.5 Pro, and Gemini 3 Pro. MiniMax used Claude Code for internal software development tasks, including code generation, analysis, and refinement. MiniMax even used prompt injections to try to trick Claude Code into believing it was a MiniMax product.
Between late 2025 and early 2026, StepFun distilled data from Claude Opus 4.1 and 4.5, Claude Sonnet 4.5, Claude Haiku 4.5, GPT-5 Mini, GPT-5 Pro, GPT-5.1, GPT-5.1 Codex, and GPT-5.2 to improve its Step 4 model’s coding and agentic functions. By mid-2026, Z.AI had distilled billions of tokens of GPT-5.5 data and Claude Opus 4.8 data to develop the CoT reasoning capabilities of its model.
[...]
Original Article
LAST CALL: Order your 2027 Scenes of South Dakota Calendars TODAY!
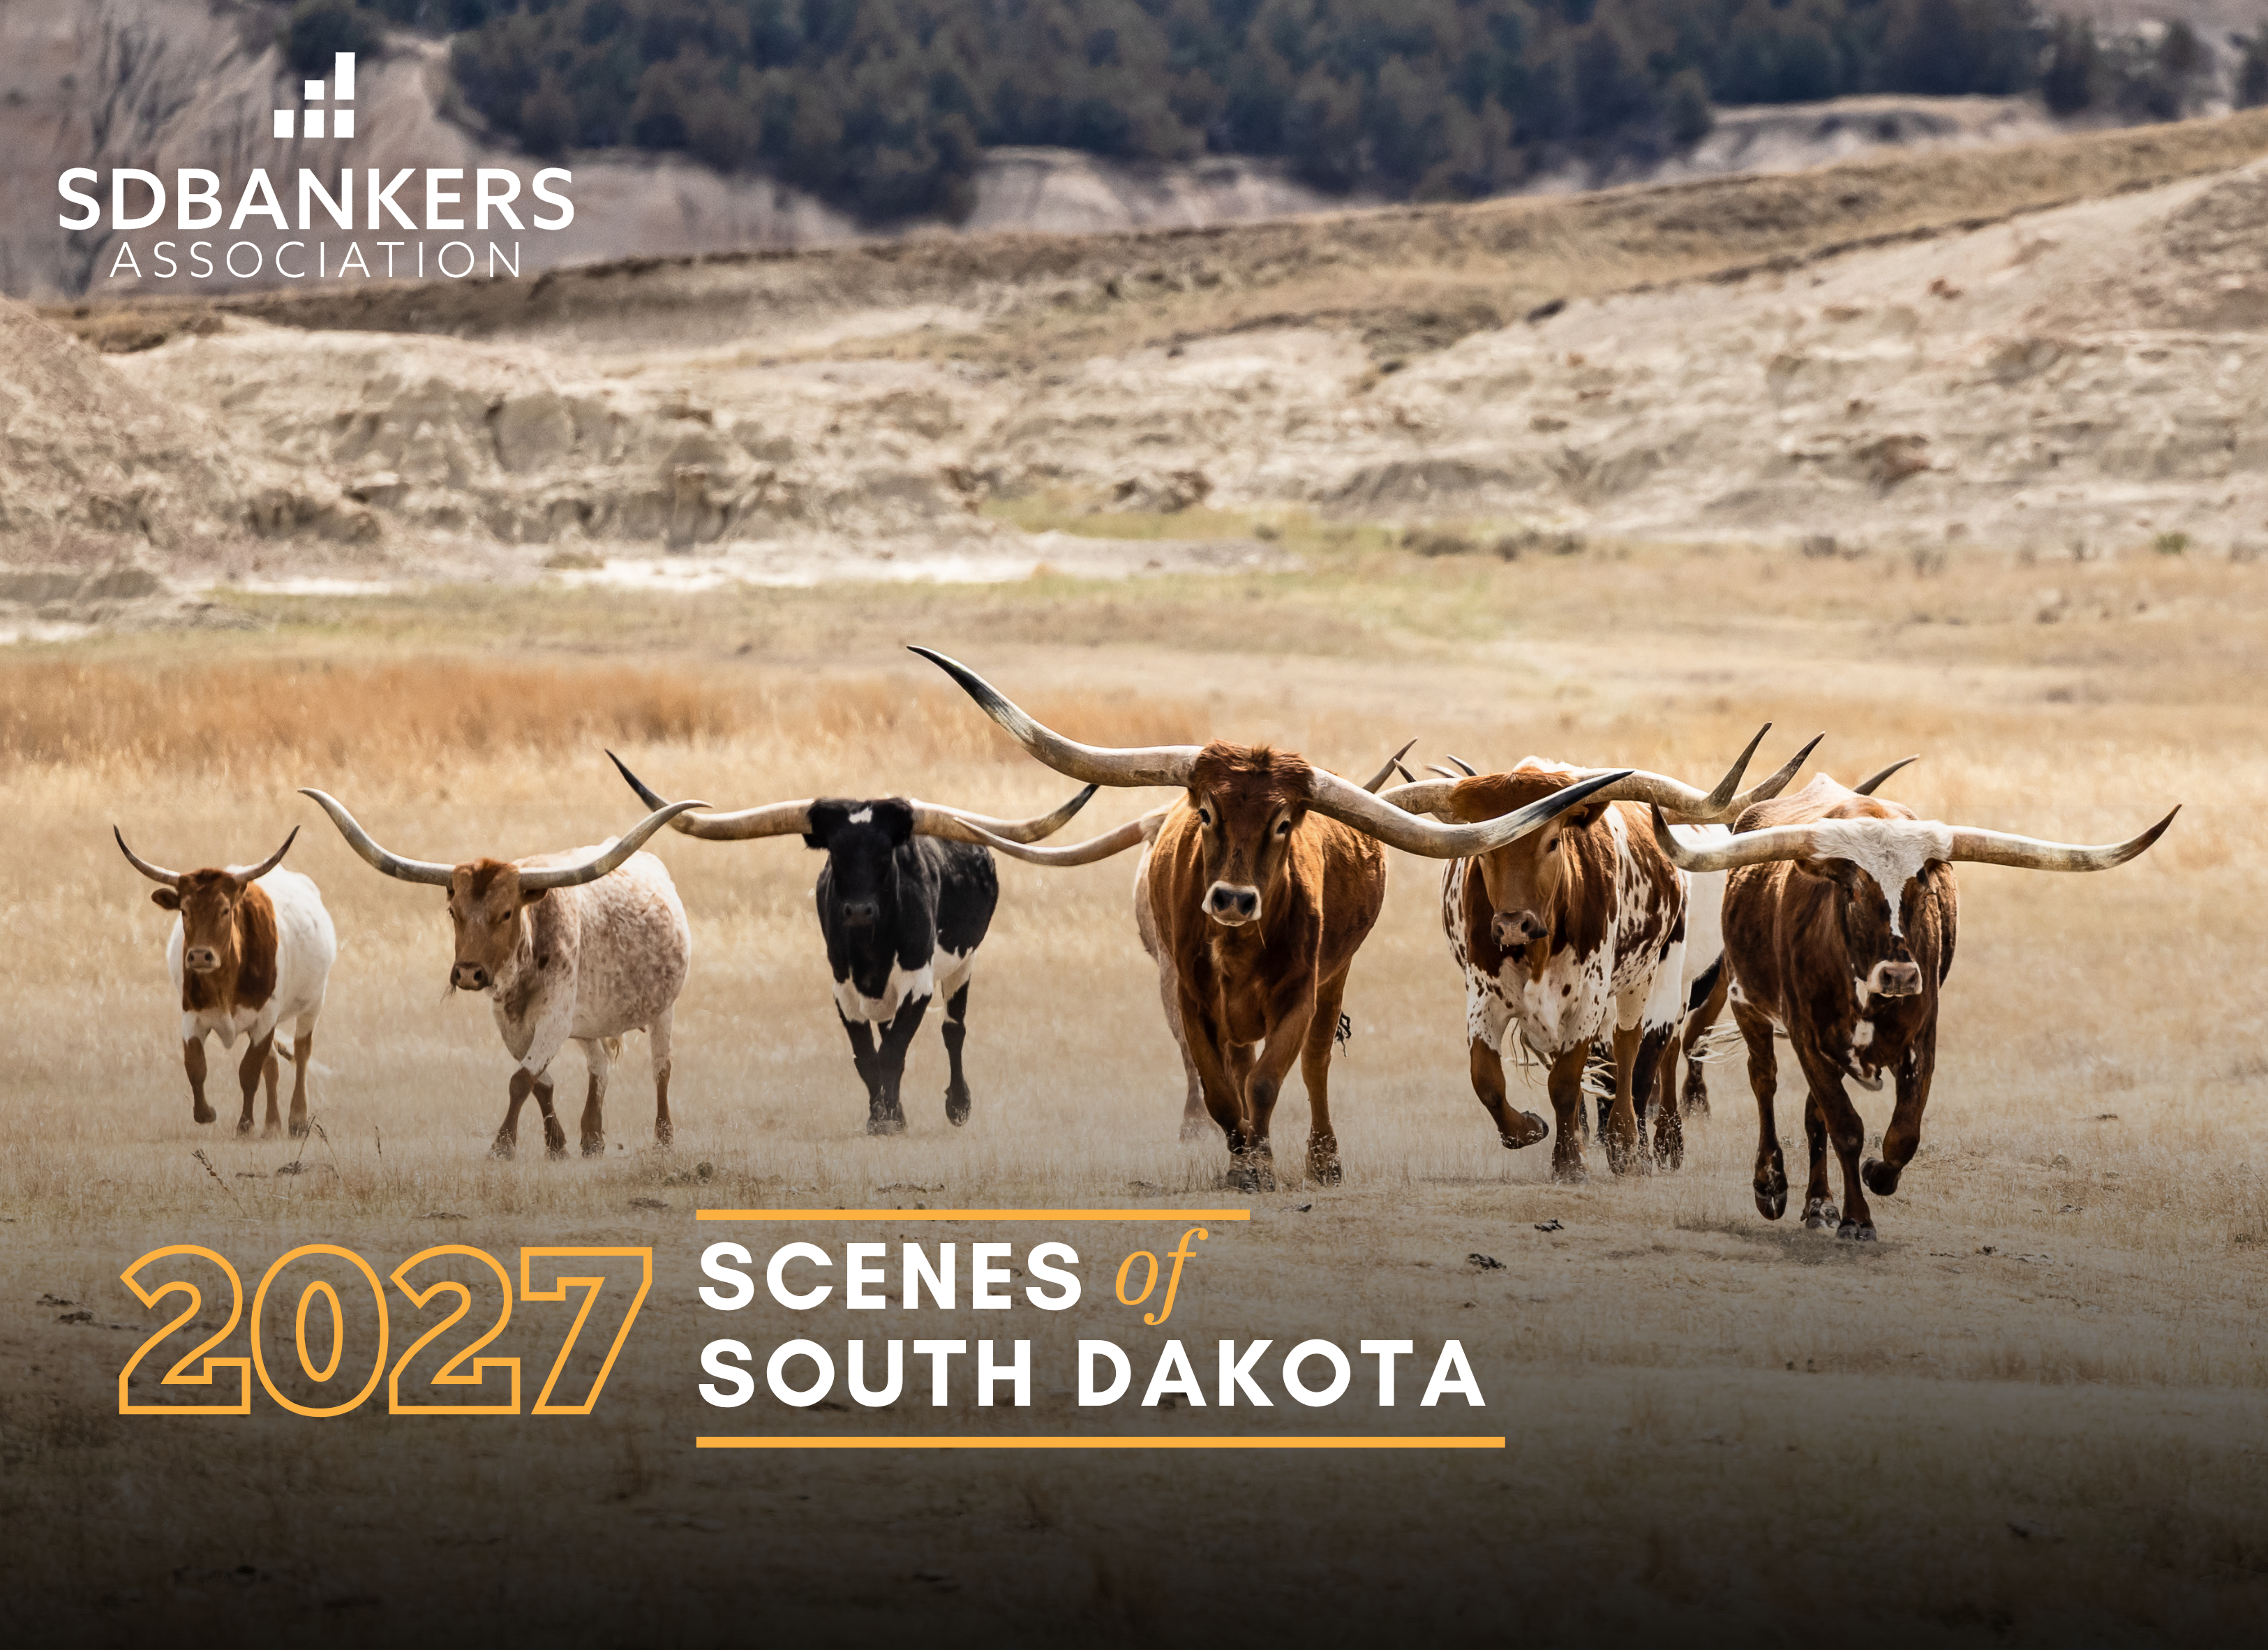 Each year, the SDBA offers the Scenes of South Dakota Calendar. This calendar features photos of South Dakota submitted by South Dakota bankers, their family members, and customers.
Scenes of South Dakota calendars are a great opportunity to thank your customers for their business and promote your bank or business. Your bank, branch, or business logo and name can be printed on each calendar to display in homes and businesses year round.
Orders are DUE SEPTEMBER 18 -- ORDER TODAY
2026 LEAD STRONG: Women in Banking Conference
September 22-23, 2026 | Sioux Falls Convention Center
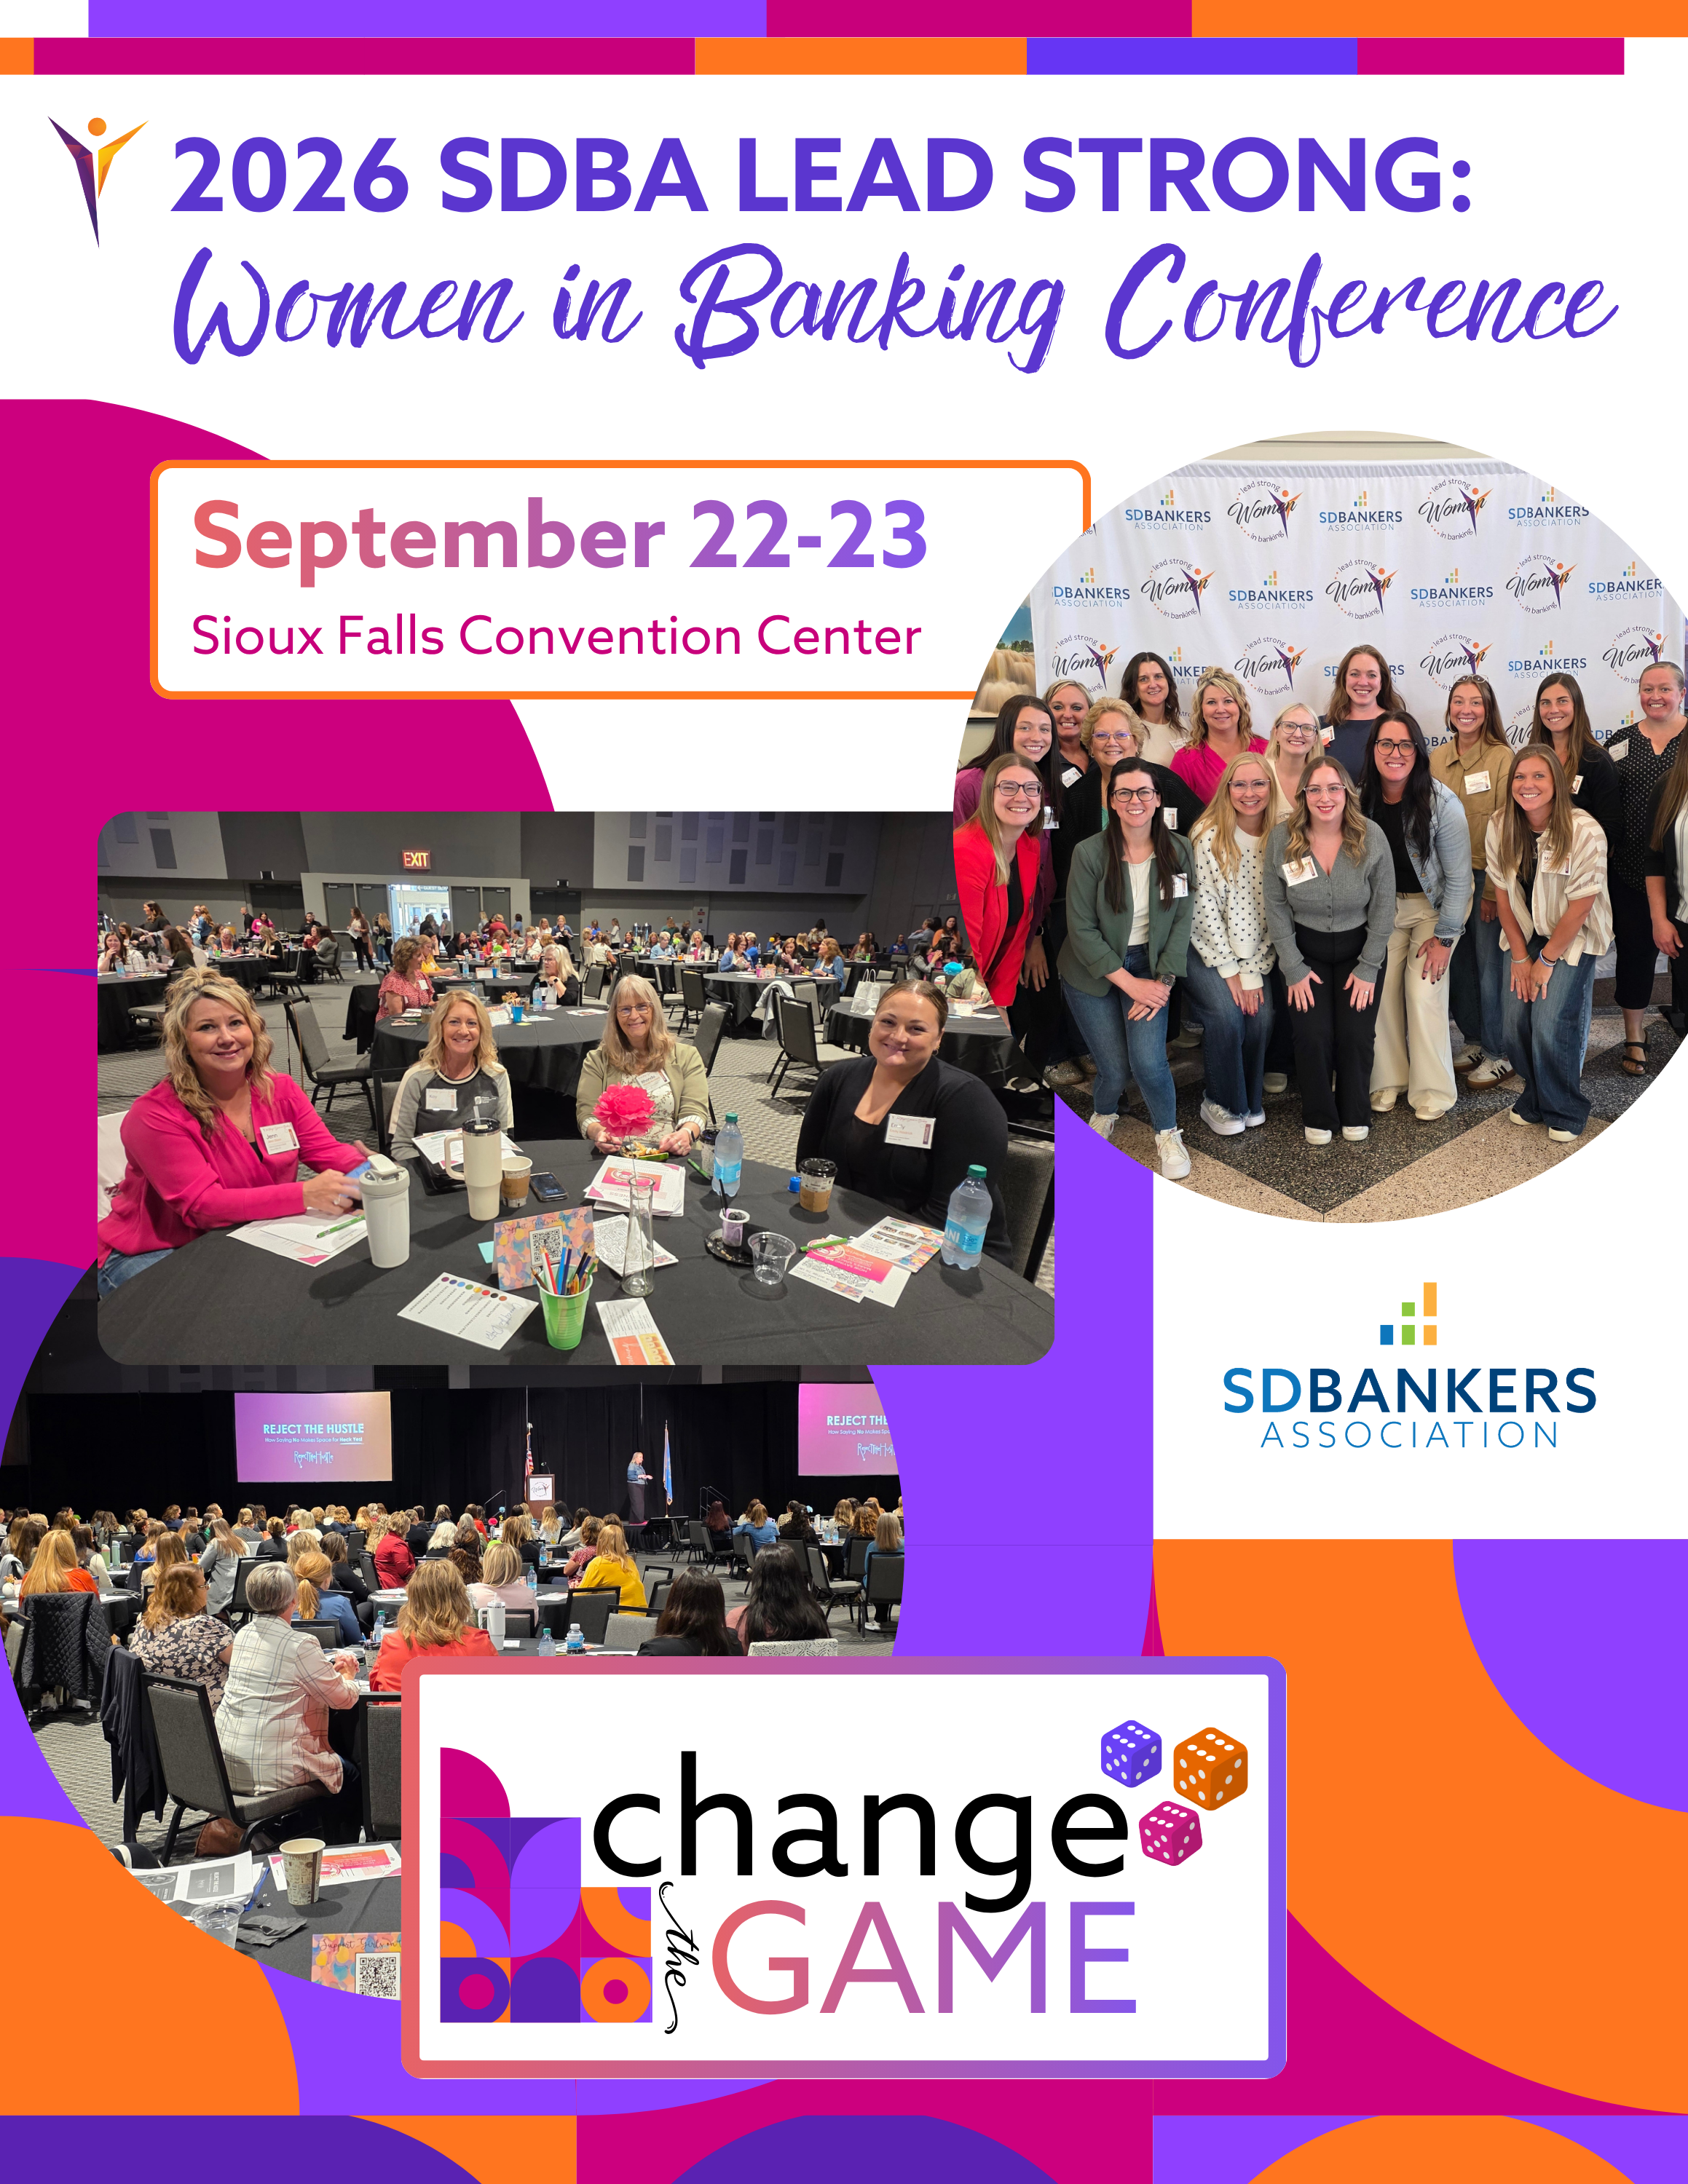
Join banking professionals from across South Dakota for Lead Strong: Women in Banking 2026, an energizing event designed to inspire growth, spark new ideas, and celebrate the power of leadership at every level. This year’s theme, Change the Game, challenges us to think differently, embrace new opportunities, and redefine what’s possible—for ourselves, our organizations, and our industry.
Through dynamic speakers, meaningful conversations, and powerful networking opportunities, you’ll hear from presenters who are breaking barriers, creating impact, and leading change in banking and beyond. Whether you’re an emerging leader, a seasoned executive, or somewhere in between, you’ll leave with fresh perspectives, practical insights, and the confidence to make your next move.
Because changing the game doesn’t require a title—it starts with a decision to lead.
Details + Registration

Participants will learn how to assess and analyze a bank’s financial performance by working with data from real institutions. Using financial statements from one sample financial institution along with statements from their own banks, participants will become familiar with the ins and outs of balance sheets and income statements and learn how to apply key performance metrics to the data presented in these documents.
Having learned how to interpret and analyze a bank’s financial statements, participants will gain deeper insight into the factors affecting bank performance. Later sessions in this course will address ways in which performance may be hindered or improved by funding strategies and risk management. Ultimately, participants will be able to review a bank’s financial statements to identify strengths and weaknesses and be able to recommend changes that will lead to improved performance.
In the final session of this course, participants will put what they have learned into practice. Participants will analyze a new data set, rate the bank’s performance and suggest strategic adjustments that might benefit the bank.
Details + Registration
2026 SDBA IRA Fall Update Seminar
November 19, 2026 | Zoom
The IRA Update builds on the attendees’ knowledge of IRA basics to address some of the more complex IRA issues their financial organizations may handle. This course includes how the SECURE Act really changes our two biggest topics: RMDs and death distributions and discusses any pending legislation. This is a specialty session; some previous IRA knowledge is assumed. The instructor uses real-world exercises to help participants apply information to job-related situations.
COURSE HIGHLIGHTS
- Death Distribution Options
- Final SECURE 2.0 changed some of the options, but how can old beneficiary options can be used.
- Creating Inherited IRA Accounts
- Reporting to IRS in the “year of death” and then “year after death.”
- Getting ready for year-end and what happens in January: Fair Market Statements, RMD notices, and 1099-Rs
- Life expectancy table! RMD calculations and inherited IRA RMD calculations change
- Amendment and plan agreement update
- Legislative update
Details + Registration
Online Education

Participating in learning opportunities outside the bank can be challenging. Take advantage of the SDBA's extensive selection of webinars and on-demand training to enhance your banking expertise directly from your computer.
GSB Online Seminars
OnCourse Learning
SBS Institute
ABA Training
Learn how to put compliance management solutions from Compliance Alliance to work for your bank, by contacting (888) 353-3933 or [email protected] and ask for our Membership Team. For timely compliance updates, subscribe to Bankers Alliance’s email newsletters.
SDBA eNews Archive
Advertising OpportunityLearn more about sponsoring the SDBA eNews
Questions/Comments
Contact the SDBA at 605.224.1653 or via email
|